Buying a house you can’t afford in British Columbia is not just a line item on a spreadsheet – it is a complex psychological and financial weight that can alter the trajectory of your life for decades. For many families in BC, the initial excitement of securing a beautiful property is quickly replaced by a persistent, underlying anxiety. This phenomenon, often referred to as mortgage suffocation, occurs when the cost of carrying a home consumes so much disposable income that basic needs, lifestyle choices, and long-term savings goals begin to erode. In an era of high-cost living and competitive real estate, understanding the difference between a dream home and a sustainable investment is critical for your well-being.
The Psychology of Ego-Driven Purchases
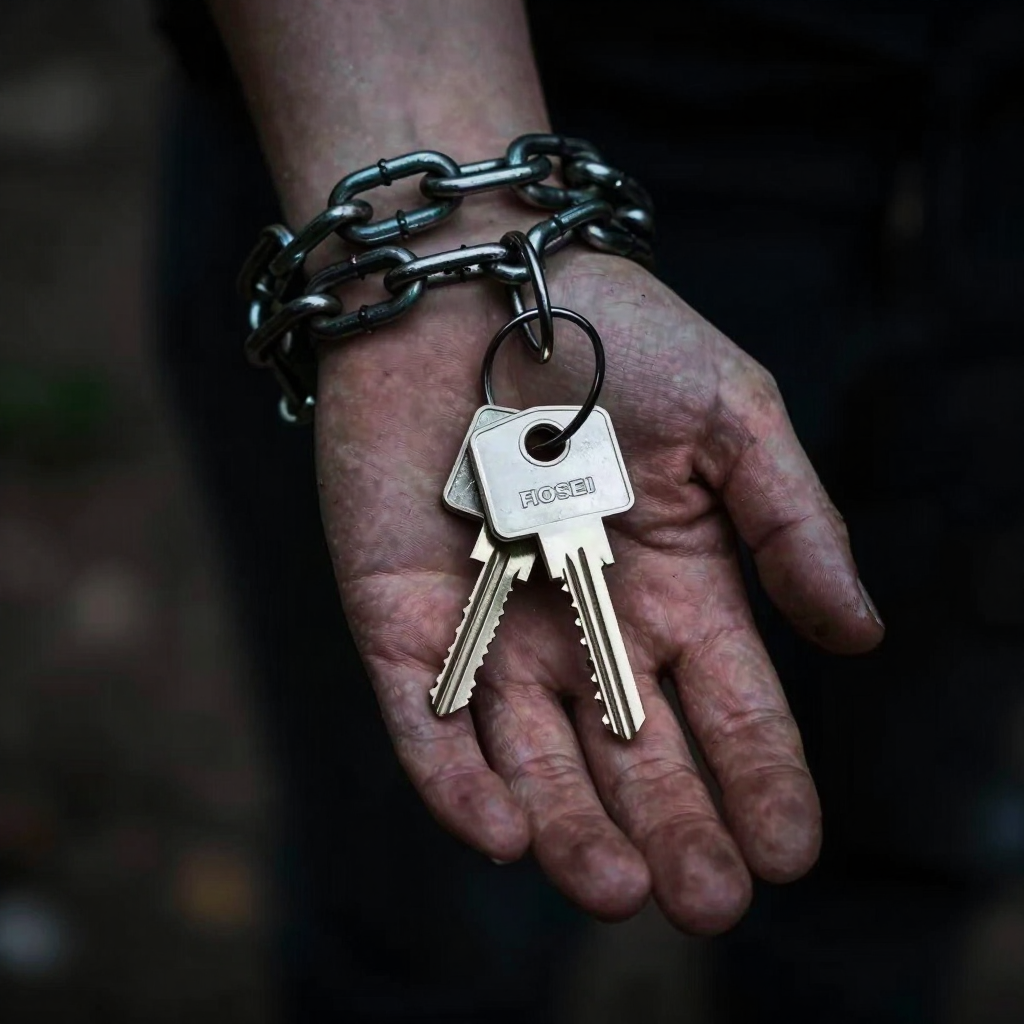
One of the most significant hurdles in the modern market is the pressure of ego-driven purchasing. We live in a visual culture where curated lifestyles are presented as standard. When you start browsing listings, it is easy to let a specific neighborhood, a certain number of bedrooms, or high-end finishes dictate your budget rather than your actual financial capacity. This leads to a dangerous situation: buyers overextending themselves before they even sign the mortgage papers. You may have secured the keys to a stunning property, but you have simultaneously locked yourself into a life of constant restriction.
When the ‘must-have’ list exceeds your sustainable spending limit, the resulting stress creates a ripple effect. Every unplanned maintenance cost, from a leaky roof to an aging HVAC system, becomes a crisis. Even minor luxuries like dining out or taking a short vacation become sources of guilt or financial strain. This is the root of mortgage suffocation. You are no longer using your home as a foundation for your life; instead, your life is being squeezed to accommodate the house. It is essential to ask yourself: is this home serving my lifestyle, or am I sacrificing my lifestyle to serve the home?
The Hidden Costs of Buying a House You Can’t Afford
Many first-time and second-time buyers focus exclusively on the monthly mortgage payment during the approval phase. However, buying a house you can’t afford often overlooks the secondary costs that compound in many British Columbia communities. Property taxes, home insurance, and utility costs for larger properties can add hundreds – sometimes thousands – of dollars to your monthly obligations. If these costs are not factored into a conservative budget, the financial pressure can become overwhelming within the first year of ownership.
Furthermore, there is the opportunity cost of over-leveraging. Every dollar that goes toward an unmanageable mortgage is a dollar that is not being invested in your retirement, your children’s education, or an emergency fund. In a volatile economic climate, having no liquid safety net is a high-risk strategy. If you experience a job loss or a sudden medical expense, a house that is already stretching your budget to its limit can quickly turn from a home into a source of foreclosure risk.
The Disappearing Advisor and the Isolation of Debt
A tragic trend in the BC real estate market is the ‘transactional’ disappearance. Once the keys are handed over and the commission is settled, many buyers find themselves without a clear roadmap for managing their new financial reality. This isolation is where many mistakes happen. Without a trusted mortgage professional to help navigate interest rate fluctuations, equity management, or refinancing options, homeowners are left to figure out complex debt structures on their own.
You need an advisor who looks beyond the closing date. When you are dealing with the consequences of buying a house you can’t afford, you need someone who can provide a clinical, objective analysis of your debt-to-income ratio and offer strategies to alleviate pressure. A true partner helps you navigate the complexities of mortgage products to ensure that your monthly payments remain predictable and manageable, even as market conditions shift.
Strategic Consolidation as a Solution
If you already feel the walls closing in due of an unmanageable mortgage or high-interest debt, there is a path forward. Many homeowners find themselves juggling multiple high-interest liabilities – such as car loans, credit cards, or lines of credit – on top of their primary residence costs. This creates a perfect storm of financial instability. Mortgage consolidation can be a powerful tool to break this cycle.
By integrating various high-interest debts into a single, structured mortgage payment, you can often secure a lower overall interest rate and create immediate breathing room in your monthly budget. Consolidation is not just about moving numbers; it is about streamlining your obligations to regain control. It allows you to stop the constant cycle of reacting to debt emergencies and start proactively managing your equity. This clarity is what separates those who are drowning in debt from those who are successfully building wealth.
Why Professional Guidance Is Non-Negotiable
Navigating the BC mortgage landscape requires a strategic roadmap, not just a loan approval. The risks associated with buying a house you can’t afford are significant, but they are also preventable with the right information at the right time. We believe in a consulting-first approach where we look at your numbers with a cold, clinical eye to ensure your lifestyle remains intact.
Our goal is to ensure that your home remains an asset that supports your goals, not a liability that consumes your peace of mind. We work with you to establish realistic boundaries and identify the most stable mortgage structures for your specific situation. Don’t let the pressure of the housing market push you into a decision you will regret in five years.
You deserve a home that reflects your reality, not just your aspirations. If you are feeling the weight of your current debt or are unsure if your dream property is actually within your reach, my team and I are here to provide clarity. Book a discovery call today or contact me for a personalized strategy session to see how we can secure your financial future.
This is such a huge topic right now with everything going on in BC. Do you think it’s better to wait for prices to dip or just try to make it work somehow? 😊
It is important to keep hidden costs like property taxes and maintenance in mind when calculating your budget. In a high-priced market like BC, these expenses can quickly impact your monthly cash flow.